Artificial intelligence is moving beyond generating content and answering questions. The emerging challenge is enabling AI systems to carry out financial transactions, interact with businesses and operate with verifiable authority. Blockchain may play an important role but only where it provides security, accountability and measurable economic value.
Publication date: Tuesday, November 10, 2026
Category: AI & Blockchain
Editorial focus: Agentic AI | Digital Identity | Autonomous Payments | Blockchain Verification | Financial Infrastructure
Artificial intelligence is entering a stage in which the most important question may no longer be what machines can generate, but what they can be trusted to do. An AI assistant that summarises a financial report presents one category of risk.
An AI agent authorised to purchase goods, move money, execute contractual instructions or interact with financial institutions presents a fundamentally different challenge. The second system does not merely produce information. It can initiate actions with real financial consequences.
This is why the convergence of artificial intelligence and blockchain deserves serious attention. Recent developments involving machine-readable payment protocols, AI-agent identity systems and programmable digital payments point toward a future in which software agents may increasingly participate in commercial transactions.
However, the central issue is not whether an AI agent can send a digital payment. It is whether the transaction can be properly authorised, independently verified, securely executed and reliably audited.
Blockchain technology may contribute to that infrastructure through tamper-evident records, programmable settlement and verifiable digital credentials but it is not a complete solution to AI security, financial fraud or operational risk.
Our central assessment is that the next stage of AI and blockchain will be determined less by technological excitement and more by whether autonomous systems can operate within trustworthy financial and legal boundaries.
Executive Summary
Artificial intelligence and blockchain are approaching an important intersection. For several years, artificial intelligence has been associated primarily with generating content, analysing information and automating business processes.
Blockchain, meanwhile, has been associated with cryptocurrencies, digital payments, tokenization and decentralised financial infrastructure. The next phase of innovation is bringing these technologies into closer contact.
The central development is the emergence of agentic AI: artificial intelligence systems capable of carrying out defined tasks and interacting with external applications on behalf of individuals or organisations. Recent announcements demonstrate why this matters.
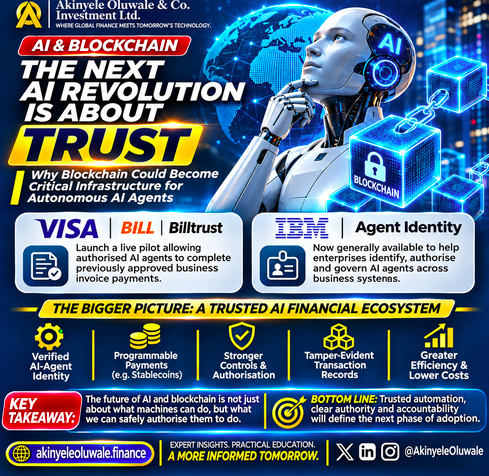
On October 20, 2026, Visa, BILL and Billtrust announced a live pilot allowing authenticated AI agents to complete previously approved business invoice payments through supplier portals.
On October 26, IBM announced the general availability of its Agent Identity solution, designed to help enterprises identify, authorise and govern AI agents operating across business systems.
These developments address a common challenge. If software can act on behalf of a person or company, how can other participants verify that the software is authorised to perform the action?
Blockchain may provide part of the answer through verifiable records, programmable financial transactions and certain forms of digital identity. However, the latest institutional developments also demonstrate that blockchain is not the only technology capable of establishing trust.
Visa's payment pilot relies on established payment infrastructure and authentication controls. IBM's identity system focuses on enterprise access governance. This distinction is important.
The opportunity for blockchain is not to replace every existing financial or identity system. It is to provide additional capabilities where distributed verification, programmable settlement or shared records offer measurable advantages.
For banks, businesses, technology providers and investors, the emerging challenge is to distinguish genuine commercial applications from speculative narratives.
Consider a simple business example. A company receives 500 supplier invoices every month. Its finance department must verify each invoice, confirm that goods or services were received, obtain the appropriate approval and arrange payment. Traditional automation can assist with parts of this process. An AI system may extract information from invoices, identify discrepancies and prepare payment instructions but what happens when the company wants the system to complete an approved payment automatically?
Several questions arise. Who authorised the AI agent. How does the supplier know the agent represents the company? What prevents the agent from exceeding its approved payment limit? How can the business establish which instructions the agent followed? And who is responsible if a payment is made incorrectly?
These questions explain why agentic AI requires more than powerful software. It requires identity, permission, accountability and financial controls. Blockchain may be useful in certain environments because it can provide shared, tamper-evident transaction records and programmable conditions. However, a blockchain record cannot independently establish that an invoice was genuine or that an AI agent correctly understood its instructions. Those matters require additional controls.
The essential lesson is that trustworthy AI depends on combining technological capability with enforceable authority and reliable oversight.
On October 20, 2026, Visa, BILL and Billtrust announced a live pilot involving AI agents completing approved invoice payments. The pilot addresses a practical problem in business payments. Many supplier portals require human users to log in and enter payment details.
That process can limit the usefulness of automated accounts-payable systems. Under the pilot, an authorised AI agent can interact with a participating supplier portal using established authentication and payment controls. The system incorporates agent recognition, tokenized payment credentials and instructions linked to previously approved invoices. This is significant because it connects AI automation with actual payment execution. However, the distinction between payment approval and payment execution must remain clear.
The AI agent is not independently deciding which invoices should be paid. It is completing payments that have already been approved by the buyer. This distinction preserves an important element of financial governance. For example, a company's finance director may approve a supplier payment of $25,000.
An authorised AI agent may then complete the approved transaction through the supplier's payment portal. The agent should not automatically have permission to increase the amount or redirect the payment to another recipient. That would require separate authority.
Why it matters: AI agents are moving into real financial workflows, but responsible adoption depends on clearly defined permissions.
On October 26, IBM announced that its Agent Identity solution had become generally available. The product addresses the growing challenge of managing AI agents within enterprise systems. Traditionally, businesses have managed access permissions for employees, contractors and software applications.
AI agents introduce another category. They may retrieve confidential information, interact with software systems and execute tasks on behalf of users. Without appropriate controls, it may become difficult to determine whether an action was performed by an employee, an authorised agent or an unauthorised system. IBM's approach focuses on agent registration, delegated authority, access enforcement and governance.
This represents an important development in enterprise security. It also provides a useful reminder that AI trust does not necessarily require blockchain. Centralised identity systems may be appropriate where an organisation controls the relevant infrastructure. Blockchain-based credentials may be useful where independent organisations need to verify information without relying entirely on a single database operator. The appropriate technology depends on the business problem.
Why it matters: The ability to identify and govern AI agents is becoming an important requirement for enterprise adoption.
Another emerging area involves connecting AI-agent identity with blockchain-based payments. Recent industry demonstrations have explored systems in which an AI agent presents verifiable credentials before initiating a stablecoin transaction. The basic idea is straightforward.
A digital service should be able to determine whether an agent is authorised to act before accepting a payment instruction. A blockchain network may then provide the settlement infrastructure. For example, an AI agent purchasing access to a digital service could potentially complete three stages:
First, establish its identity. Second, demonstrate that it has permission to make the purchase. Third, complete the payment using an approved digital settlement mechanism.
This could become relevant to machine-to-machine commerce, where software applications purchase services from other applications. However, experimental demonstrations should not be confused with mature commercial adoption.
A working demonstration establishes technical feasibility under particular conditions. It does not necessarily establish large-scale customer demand, legal enforceability or sustainable profitability.
Why it matters: Combining verifiable identity with programmable payments could support new digital business models, but commercial validation remains necessary.
Stablecoins may become useful in certain AI-driven payment applications. A stablecoin is a digital token designed to maintain its value relative to a reference asset, such as a national currency.
For machine-to-machine payments, stablecoins may offer features including programmable transfers and the ability to settle transactions across supported digital networks. Consider a hypothetical AI research application. The application needs to purchase a small amount of computing capacity from another service. Instead of entering into a conventional monthly billing arrangement, the system might pay for each authorised unit of service.
A programmable payment mechanism could support that process. However, stablecoin settlement introduces its own risks. These include issuer risk, redemption arrangements, transaction errors, custody, regulatory compliance and operational security. The speed of a blockchain transfer does not automatically resolve these issues.
Furthermore, conventional payment systems may already provide suitable solutions for many business transactions. The relevant question is whether stablecoins offer a demonstrable improvement in a particular application.
Why it matters: Stablecoins could support machine-based commerce, but their economic usefulness must be evaluated against existing payment alternatives.
As AI agents gain access to financial systems, companies must establish stronger governance arrangements. This involves more than cybersecurity. A secure system must also establish who is accountable for an agent's actions. For example, an AI agent may receive an instruction to purchase a service.
The agent might misunderstand the instruction, select an unsuitable supplier or attempt a transaction beyond its permitted authority. Even if the underlying payment network operates correctly, the business may still suffer a financial loss. The problem is not necessarily a failure of the payment system. It may be a failure of the decision-making or authorisation process. This is why companies are developing systems that separate identity, permission, execution and monitoring.
Blockchain may provide useful evidence of completed transactions but preventing unauthorised actions also requires controls before execution.
Why it matters: The next stage of AI adoption will depend on whether organisations can control what autonomous systems are allowed to do.
Artificial intelligence and blockchain should not be treated as interchangeable technologies. They perform different functions. Artificial intelligence can interpret information, identify patterns, generate recommendations and carry out certain automated tasks. Blockchain can support shared transaction records, digital asset transfers and programmable execution. When combined appropriately, these technologies may complement each other. However, the relationship should not be exaggerated.
An AI system does not automatically become trustworthy because it uses blockchain. Similarly, a blockchain network does not automatically become intelligent because it incorporates AI. Consider a hypothetical international trading company. An AI agent could review a supplier invoice and compare it with an approved purchase order.
A separate identity system could verify the agent's authority. A payment system could execute the approved transaction. A blockchain network might record or settle the transfer if that provides a commercial advantage. The result would be a coordinated financial process involving several technologies but the business must still verify the supplier, establish appropriate payment limits and maintain effective internal controls.
The strongest future applications are likely to emerge where each technology performs a clearly defined function.
This could create demand for stronger authentication, transaction monitoring and delegated-authority controls. However, banks must preserve accountability and comply with existing financial regulations.
The commercial opportunity lies in reducing manual processing while maintaining security and transaction visibility.
However, increased AI adoption does not automatically establish demand for every blockchain token.
Their success will depend on reliable reserves, redemption arrangements, liquidity and compliance.
However, management must establish approval limits, monitoring arrangements and accountability.
These systems could become important components of enterprise AI infrastructure.
Potential applications include invoice processing, treasury operations and cross-border business services.
However, implementation must reflect local regulatory requirements, financial infrastructure and operational conditions.
At Akinyele Oluwale & Co. Investment Ltd., we believe the convergence of AI and blockchain represents a meaningful area of financial innovation.
However, the industry must avoid a familiar mistake. New technology does not automatically create economic value. A business does not become more profitable simply because it introduces AI. A payment system does not become more reliable simply because it uses blockchain and a digital asset does not become a sound investment merely because its project claims to support autonomous agents.
The relevant question is whether the technology solves a genuine problem. Consider a company processing thousands of supplier invoices. If AI automation reduces processing time, improves accuracy and maintains strong approval controls, the company may achieve measurable benefits. If blockchain settlement further reduces reconciliation costs or improves transaction visibility, it may add value but if the combined system introduces greater complexity, higher costs or new security risks without corresponding benefits, the business case may be weak.
This is why institutional adoption should be evaluated through operational evidence. We believe five principles should guide the development of AI-enabled financial systems.
First, authority must be explicit. An AI agent should operate only within permissions granted by the responsible person or organisation.
Second, financial controls must remain enforceable. Automated execution should not bypass appropriate approval procedures.
Third, accountability must be clear. Organisations must establish responsibility for errors, unauthorised actions and disputes.
Fourth, technology should be proportionate to the problem. Blockchain should be used where its capabilities provide genuine advantages over simpler alternatives.
Fifth, commercial benefits must be measurable. Efficiency, reliability, cost and customer outcomes should determine success.
These principles are particularly important as financial institutions consider allowing autonomous systems to interact with sensitive financial infrastructure.
Our editorial assessment is that the most valuable AI and blockchain businesses will not necessarily be those promising the greatest level of autonomy. They will be those demonstrating the strongest combination of useful automation, financial control and institutional trust.
Several developments deserve attention during the remainder of November 2026 and into 2027.
Visa's AI payment pilot: Monitor whether the Visa, BILL and Billtrust initiative expands beyond its initial participating businesses.
Enterprise agent identity: Watch how companies adopt systems such as IBM Agent Identity to manage permissions and accountability.
Stablecoin settlement: Look for evidence that AI-driven stablecoin payments are being used for genuine commercial activity.
Digital credentials: Monitor progress in verifying AI-agent identity and delegated authority across different platforms.
Regulatory treatment: Assess how financial regulators address responsibility for AI-initiated transactions.
Fraud prevention: Watch for improved systems that distinguish authorised agents from malicious automated activity.
Payment disputes: Examine how businesses resolve incorrect or unauthorised AI-initiated transactions.
Interoperability: Monitor whether competing AI and payment systems can operate together securely.
Commercial performance: Look for independently verifiable improvements in processing costs, transaction accuracy and operational efficiency.
These developments will provide a more reliable picture of adoption than speculative market commentary.
AI is moving from information generation toward executing authorised business tasks.
Visa, BILL and Billtrust launched a live pilot for AI-initiated payments on October 20, 2026.
The pilot involves payments already approved by buyers; it does not give agents unrestricted payment authority.
IBM made its Agent Identity solution generally available on October 26, 2026.
AI-agent identity, delegated permissions and accountability are becoming important enterprise requirements.
Blockchain may support verifiable records and programmable settlement in suitable applications.
Stablecoins could support certain machine-to-machine payments but introduce financial and operational risks.
Blockchain is not necessary for every AI payment or identity application.
Institutional AI adoption does not automatically increase the investment value of associated cryptocurrencies.
The long-term opportunity lies in secure, accountable and commercially useful automation.
Akinyele Oluwale & Co. Investment Ltd. is an institutional financial intelligence platform focused on global financial markets, macroeconomics, central banking, institutional cryptocurrency, stablecoins, tokenization, real-world assets, artificial intelligence and blockchain technology.
Our editorial mission is to explain consequential financial developments through evidence-based research, practical education and an institutional perspective. We examine how emerging technologies, financial institutions and regulatory frameworks interact to shape the future of global finance.
AI systems are becoming capable of interacting with financial services and executing previously approved transactions.
Payment networks are exploring how those systems can operate securely. Enterprise technology providers are developing stronger identity and governance arrangements and blockchain-based payment infrastructure may provide useful capabilities in certain automated commercial environments.
However, the next stage of adoption will require more than technological sophistication. Businesses must establish who controls an AI agent. Financial institutions must verify what the agent is authorised to do. Payment systems must protect transaction integrity and regulators must consider accountability when automated systems make mistakes.
These requirements will determine whether AI-enabled financial services become dependable commercial infrastructure.
The future of AI and blockchain will not be defined by machines gaining unlimited financial autonomy. It will be defined by whether organisations can make automated financial decisions and transactions more efficient without sacrificing human accountability, legal certainty or financial control.
That is where the next phase of institutional innovation is taking shape.
Observe the change. Understand the implications. Position with discipline.
Akinyele Oluwale & Co. Investment Ltd.
Where Global Finance Meets Tomorrow's Technology.
Website: akinyeleoluwale.finance
Editorial disclaimer: This article provides general financial education and technology analysis. It does not constitute personalised investment advice or an endorsement of any particular cryptocurrency, token or technology provider.