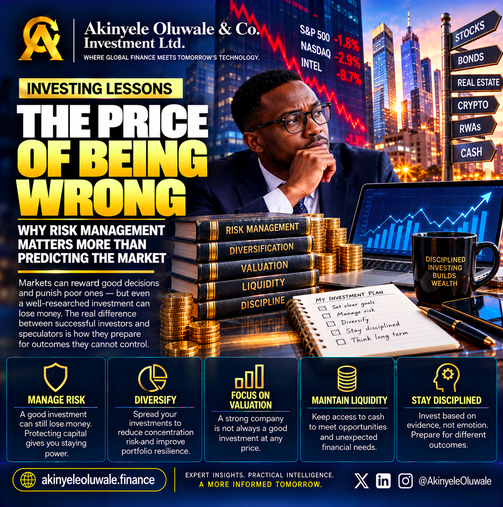
Markets can reward good decisions and punish poor ones but even a well-researched investment can lose money. The difference between disciplined investing and speculation is often how investors prepare for outcomes they cannot control.
Published: October 31, 2026 | Category: Investing Lessons | By: Akinyele Oluwale
This Saturday's investing lesson examines an issue that matters across stocks, bonds, cryptocurrency, property and other financial assets: protecting capital when markets behave differently from expectations.
The article will connect recent financial-market developments with practical lessons in portfolio construction, diversification, liquidity, valuation and investment discipline.
Executive Summary
Friday, October 30, 2026, offered investors a powerful reminder that financial markets do not reward optimism indefinitely.
US stocks fell sharply as investors questioned whether the enormous amounts being spent on artificial intelligence would translate into sufficient future profits.
The S&P 500 declined approximately 1.8%, while the technology-heavy Nasdaq fell about 2.9%. Intel suffered a particularly severe decline following disappointing financial guidance.
Meanwhile, US Treasury securities attracted demand as investors reconsidered their exposure to riskier assets.
The developments came just two days after the US Federal Reserve maintained its benchmark interest-rate target at 3.75%–4.00%, citing continuing inflation concerns and economic uncertainty.
These events illustrate a central investing principle:
Being confident about an investment theme is not the same as being protected against financial loss.
Artificial intelligence may continue transforming businesses and economies. That does not mean every AI-related company represents an attractive investment at every price.
Similarly, government bonds may offer diversification benefits, but they are not entirely free from market risk.
Investors must therefore distinguish between a promising economic story and a sound investment decision.
Successful investing requires more than identifying opportunities.
It requires understanding valuation, managing exposure, preserving liquidity and preparing for unfavourable outcomes.
For individuals, business owners and institutional investors, the most important question is not simply how much an investment could earn.
It is also how much capital could be lost and whether that loss would threaten future financial objectives.
Imagine two investors.
Both believe artificial intelligence will become an increasingly important part of the global economy.
The first investor puts nearly all available investment capital into a handful of AI-related companies.
The second investor shares the same long-term conviction but recognises that share prices can move independently of technological progress.
The second investor therefore evaluates valuations, maintains appropriate liquidity and spreads investment exposure across assets with different risk characteristics.
If technology shares decline sharply, both investors may experience losses.
However, their financial positions could be very different.
The first investor may face substantial portfolio losses because of excessive concentration.
The second investor may also lose money, but diversification and liquidity could provide greater flexibility.
This example demonstrates why investment discipline matters.
An investor can be correct about the long-term development of an industry and still lose money by purchasing assets at excessive prices.
A strong company is not automatically a good investment at any valuation.
Equally, a promising investment can become unsuitable if the investor cannot afford to withstand its potential losses.
Investment quality depends on the relationship between price, expected return, risk and financial objectives.
On October 30, US equity markets declined amid concerns about the financial returns from major artificial-intelligence investments.
The S&P 500 fell approximately 1.8%, while the Nasdaq declined about 2.9%.
Intel's shares suffered a particularly sharp decline after disappointing guidance, reinforcing concerns about earnings, spending and profitability.
The market reaction demonstrated that investors were increasingly examining whether corporate investment in AI could generate adequate returns.
This does not establish that artificial intelligence has failed as a technology.
It shows that financial markets can reassess how much they are willing to pay for expected future earnings.
On October 28, the Federal Reserve maintained its federal funds target range at 3.75%–4.00%.
The central bank acknowledged continued economic expansion but also highlighted elevated inflation and uncertainty.
For investors, the decision reinforced the importance of interest rates in determining asset valuations.
Higher interest rates can increase financing costs and make future corporate earnings less valuable in present-value terms.
They can also influence the relative attractiveness of bonds and equities.
The International Monetary Fund's October 2026 Global Financial Stability Report identified vulnerabilities involving concentrated market exposures, leverage, sovereign bond yields and potential corrections in AI-related assets.
The broader lesson is that financial-market risks often interact.
A change in interest rates may influence bond prices.
Bond-market volatility may affect liquidity.
Liquidity pressures may force investors to sell other assets.
An apparently isolated market event can therefore have consequences across several asset classes.
For investors, this makes portfolio resilience essential.
Consider a company expected to earn ₦100 million annually.
Suppose its market value is ₦1 billion.
Ignoring differences in accounting and capital structure, the implied price-to-earnings multiple would be:
₦1 billion ÷ ₦100 million = 10 times earnings.
Now suppose enthusiasm pushes the company's valuation to ₦3 billion while its earnings remain unchanged.
The multiple becomes:
₦3 billion ÷ ₦100 million = 30 times earnings.
The business has not necessarily become three times more profitable.
Investors are simply paying more for each naira of current earnings.
That higher valuation may be justified if future earnings grow sufficiently.
But if growth disappoints, the share price could decline even if the company remains profitable.
This is why valuation matters.
A good business purchased at an unreasonable price can produce a disappointing investment return.
Diversification means spreading investments across different exposures rather than depending excessively on one asset, company, sector or source of risk.
For example, a portfolio concentrated entirely in technology shares may be vulnerable to a broad decline in technology valuations.
A more diversified portfolio may contain assets influenced by different economic conditions.
However, diversification is not a guarantee against losses.
During major financial crises, several asset classes may decline simultaneously.
The objective is to reduce unnecessary dependence on a single outcome.
Liquidity refers to the ability to access cash or sell an asset without excessive delay or price disruption.
Suppose a business owner invests all available funds in long-term assets.
The investments may have attractive expected returns.
But if the business suddenly requires money for salaries, inventory or urgent expenses, the owner may have to sell investments at an unfavourable time.
The problem is not necessarily that the original investments were poor.
The problem is that the investor failed to match investment commitments with financial obligations.
This is particularly important for entrepreneurs.
Business working capital should not be confused with surplus investment capital.
A company that earns attractive returns on investments but cannot meet immediate obligations may still experience financial distress.
This is one of the most important mathematical lessons in investing.
Assume an investment is worth ₦1,000,000.
If its value falls by 20%, the investment becomes worth ₦800,000.
To return to ₦1,000,000, the investor needs to earn ₦200,000.
But ₦200,000 represents 25% of ₦800,000.
Therefore, a 20% loss requires a 25% gain to recover.
The relationship becomes more demanding as losses increase.
| Portfolio loss | Gain required to recover |
|---|---|
| 10% | 11.1% |
| 20% | 25.0% |
| 30% | 42.9% |
| 40% | 66.7% |
| 50% | 100.0% |
The figures illustrate why avoiding excessive losses is so important.
An investor who loses half of a portfolio's value must double the remaining capital merely to return to the original amount.
This does not mean investors should expect to avoid all losses.
It means they should understand how losses affect long-term financial progress.
Leverage involves using borrowed funds to increase financial exposure.
It can amplify gains when investments perform well.
It can also amplify losses when prices decline.
For example, suppose an investor uses ₦500,000 of personal capital and borrows another ₦500,000 to purchase assets worth ₦1 million.
If those assets fall by 20%, their value becomes ₦800,000.
Ignoring interest and transaction costs, the investor still owes ₦500,000.
The remaining equity is ₦300,000.
Although the assets declined by 20%, the investor's personal capital declined from ₦500,000 to ₦300,000—a loss of 40%.
Leverage magnifies the consequences of market movements.
For this reason, borrowed capital should never be mistaken for increased investment strength.
Financial markets frequently develop powerful narratives.
Artificial intelligence will transform industries.
Blockchain will modernise financial infrastructure.
Renewable energy will reshape electricity markets.
Digital payments will become more efficient.
Some of these developments may create genuine long-term economic value.
But an investment decision requires additional questions.
What is the asset worth?
What earnings or cash flows support that valuation?
How much growth is already reflected in the price?
What could go wrong?
What financial obligations must the investor meet?
A convincing story is not a substitute for financial analysis.
Recent developments offer lessons across several asset classes.
Equities: Companies with ambitious growth expectations may face significant price corrections if earnings fail to justify valuations.
Government bonds: Bonds may attract demand during periods of market uncertainty, but their prices remain sensitive to interest rates, inflation and credit considerations.
Cryptocurrencies: Digital assets can experience substantial volatility and may be affected by liquidity conditions, investor sentiment and changes in financial regulation.
Real estate: Property investments may provide long-term economic value, but investors must consider financing costs, rental income, maintenance and the difficulty of selling quickly.
Private businesses: Entrepreneurs must balance investment opportunities against working-capital requirements and debt obligations.
Cash and short-term instruments: Liquidity can provide flexibility, although inflation and currency depreciation may reduce purchasing power over time.
The appropriate balance among these exposures depends on an investor's objectives, circumstances, time horizon and ability to bear losses.
No single asset class is suitable for every investor.
At Akinyele Oluwale & Co. Investment Ltd., we believe one of the most damaging misconceptions in investing is that successful investors must always predict market movements correctly.
They do not.
Financial markets contain uncertainty that even experienced professionals cannot eliminate.
A well-researched investment may decline because of unexpected economic developments, regulatory changes or shifts in investor expectations.
The purpose of investment analysis is therefore not to achieve perfect forecasting.
It is to improve the quality of decisions made under uncertainty.
For business executives, this principle is especially important.
Before committing capital to a new project, management should examine expected cash flows, financing costs, downside scenarios and the project's effect on the company's overall financial position.
An attractive projected return means little if the investment creates an unacceptable risk of financial distress.
The same discipline applies to personal investing.
A portfolio should reflect actual financial circumstances rather than the desire to outperform other investors.
There is no economic benefit in achieving an impressive short-term return if the underlying exposure threatens essential financial commitments.
The strongest investment decisions are those that remain financially manageable even when the original assumptions prove wrong.
This is not pessimism.
It is disciplined capital management.
Investors should pay attention to several developments in the coming weeks.
Corporate earnings: Financial results from major technology companies will provide further evidence about the profitability of AI-related spending.
Central-bank decisions: Interest-rate policy will continue influencing borrowing costs, bond valuations and investor expectations.
Inflation: Persistent inflation may affect household purchasing power, business margins and monetary policy.
Government bond yields: Significant changes in yields can influence the valuation of financial assets and the cost of capital.
Market concentration: Heavy dependence on a small group of companies or investment themes can increase portfolio vulnerability.
Liquidity conditions: Changes in financial-market liquidity can amplify price movements and affect the ability to sell assets.
Geopolitical developments: Energy-market disruptions and international tensions may influence inflation, corporate costs and investor confidence.
Investors should evaluate these developments in relation to their financial objectives rather than treating every headline as a reason to make immediate portfolio changes.
A promising investment theme does not guarantee attractive investment returns.
Valuation matters because investors can overpay for otherwise strong businesses.
Diversification can reduce concentration risk, although it cannot eliminate losses.
Liquidity is essential for meeting financial obligations and avoiding forced asset sales.
Portfolio losses require proportionately larger gains to recover.
Borrowing to invest can magnify financial losses.
Market predictions should not replace careful analysis of financial risks.
Long-term investment success depends on disciplined decisions, realistic expectations and sound capital management.
Investors should distinguish between temporary market volatility and a permanent deterioration in an asset's underlying economic value.
Protecting financial flexibility is often more important than pursuing the highest possible short-term return.
Akinyele Oluwale & Co. Investment Ltd. is an institutional financial intelligence and investor-education platform covering global markets, macroeconomics, digital finance, blockchain, institutional cryptocurrency, stablecoins and real-world asset tokenization.
Our mission is to explain financial developments clearly, examine their economic implications and promote evidence-based financial decision-making.
We believe investing should be approached with financial discipline, independent analysis and a realistic understanding of uncertainty.
The financial markets will always provide new opportunities.
There will be emerging technologies, promising companies, expanding industries and periods of extraordinary investor enthusiasm.
Some opportunities will produce lasting economic value.
Others will disappoint.
The challenge is that investors cannot know every outcome in advance.
What they can control is the quality of their analysis, the amount of risk they accept and the financial commitments they make.
A disciplined investor does not need to predict every market correction.
A disciplined investor needs a financial approach that can withstand uncertainty.
Wealth creation is important. But preserving the capacity to build wealth over time is equally important.
Observe the change. Understand the implications. Position with discipline.
Akinyele Oluwale & Co. Investment Ltd.
Where Global Finance Meets Tomorrow's Technology.